DailyPay On-Demand Pay
DailyPay IncFinanceVerified
- 17.50K Reviews
- 4.7
- Downloads
- 1,000,000+
- Price
- Free
Screenshots
 Analysis by Appwesome
When bills and payday refuse to line up, it’s tempting to treat any early access to wages as extra money. I’d approach DailyPay On-Demand Pay differently: as a way to change when some earned pay reaches you, not as a raise or a replacement for planning. That distinction matters in a shared household, where one person’s quick transfer can affect how everyone covers groceries, transport, and upcoming bills.
A household expense that cannot wait
Imagine you share rent and household costs with a partner or roommate. A necessary car repair lands a few days before payday, and you have already worked the shifts that earned the money you need. DailyPay may give you another timing option: check what is available and decide whether taking some of it now makes more sense than using a credit card or asking someone else to cover the bill.
I would keep the decision specific. Work out the repair amount, check which regular expenses still need to be paid before payday, and avoid transferring more than the immediate gap requires. Early access can solve a timing problem, but it does not increase the total pay coming from that work. The next paycheck may therefore be smaller than you expect if you have already moved part of it forward.
One account, one person’s financial boundary
In a household, shared bills do not mean shared financial accounts. I’d keep the app and its sign-in under the employee’s control rather than treating it like a joint household wallet. A partner can help compare the upcoming expenses, but the person whose wages are involved should make and confirm any transfer themselves.
That boundary is practical as well as personal. It helps avoid confusion about who requested money, which expenses it was intended to cover, and what remains for payday. I would not leave a financial app signed in on a shared device just because everyone trusts one another; a lock screen and separate user accounts where available are sensible habits for any money-related service.
How Does It Work?
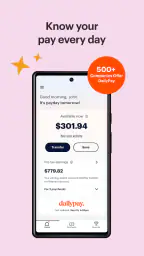
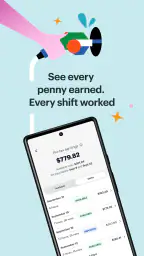
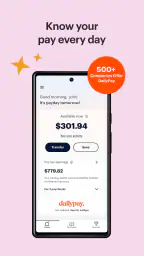
Picture this: you’ve worked extra hours this week and could really use that cash now instead of waiting for the end of the pay period. With DailyPay On-Demand Pay, you can access your earned wages whenever you need them. The app syncs with your employer's payroll system, giving you real-time updates on what you’ve earned. It’s like having a digital ATM that opens whenever you need it.
The Setup Process
Getting started with DailyPay is pretty straightforward. You download the app, create your account, and link it to your employer’s payroll system. Boom! You’re ready to access your earnings. The interface is clean and user-friendly, which is a huge plus for someone like me who isn’t super tech-savvy.
Other Stories to Read




For a household, the first useful question is not just whether the app looks simple, but whether the employee can connect it through their own work arrangement. I’d start by checking with the employer or the relevant workplace channel, then use the employee’s own details rather than trying to set it up as a shared family account. That avoids mixing one person’s payroll access with another person’s phone or login.
Features to Love
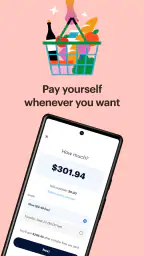
One of my favorite features is the next-day transfer option. Need money for an unexpected expense? No problem! With just a few taps, you can transfer your earnings to your bank account by the next day. There’s also a same-day transfer option if you’re in a bind and can’t wait.
The choice between waiting and moving money sooner is worth pausing over. If an expense is due tomorrow, a next-day option may be enough; if it is due today, the faster route may be more relevant, but urgency alone does not make every transfer worthwhile. I’d check the amount, timing, and any terms shown in the app before confirming, then compare that choice with the cost and consequences of the alternative, such as a late bill payment.
Beyond just accessing your earnings, the app also offers budgeting tools. You can track your spending habits and see where your money goes each month. This feature has helped me cut back on unnecessary expenses and save more.
A practical way to use those tools is to review spending before deciding how much to take early. Looking at the month as a whole can reveal whether the immediate problem is a one-off bill or a recurring mismatch between pay dates and expenses. If it keeps happening, I’d treat that pattern as a prompt to adjust bill timing or the household budget, rather than relying on early access every cycle.
Security and Privacy
Security is a big deal for any financial app, and DailyPay doesn’t disappoint. The app uses bank-grade security to protect your data. I felt confident knowing my personal information was safe and secure.
That confidence should go together with ordinary account care, especially if a phone is passed around at home. I’d avoid sharing passwords, sign out before handing a device to someone else, and make sure notifications do not expose financial details on a lock screen. Those are sensible precautions, not a reason to assume that a trusted household member needs access to the employee’s account.
Coordination without turning pay into a group decision
When money is tight, a short conversation before a transfer can prevent a second problem later. If you and another adult split bills, agree which expense the early funds will cover and record that in whatever household budget you already use. That keeps the transfer tied to a concrete need instead of making it feel like general spending money.
I would also agree on what happens at payday. For example, if one person advances earnings to cover a shared utility bill, note that the bill has already been handled so nobody pays it twice or counts the same funds toward another purchase. This is simple coordination, not a special feature of the app, and it works best when each person understands that the early transfer comes from wages already earned.
User Experience
Using the app is a breeze, thanks to its intuitive design. Everything is laid out clearly, and the navigation is seamless. Whether you’re checking your balance, transferring funds, or setting up a budget, it’s all just a few clicks away. Plus, their customer support is top-notch. I shot them a quick question and received a helpful response almost immediately.
For someone deciding whether to install it, the basic product details are reassuringly clear: DailyPay is a free finance app from DailyPay Inc, with a 4.7 average from around 215,000 ratings and over 1 million installs. It is rated for Everyone, and its current version is 44.0.0. Those figures suggest that it is widely used, but popularity cannot tell you whether your own employer connection and pay routine make it a good fit.
Age, trust, and who should use it
The Everyone age label describes the app’s content rating; it does not make the service a household budgeting tool for children. The sensible user is the employee whose wages are being accessed. I would not let a child or another household member make transfer decisions, even if they help with errands or use the same phone for other tasks.
DailyPay is most relevant to workers who sometimes face a short gap between earned pay and an unavoidable expense, and whose employer supports the arrangement. It may also suit people with changing hours who want a clearer view of earned wages as the pay period progresses. By contrast, it is not the right answer if you need money beyond what you have earned, if you are looking for a loan, or if your employer does not support the service.
How it compares with familiar alternatives
Compared with waiting for the normal payday, the appeal is timing: the app can make some earned wages available earlier. Compared with borrowing on a credit card or asking a friend to bridge a bill, it draws on your own wages rather than creating the same kind of debt or personal IOU. Those options are not interchangeable, though. A credit card may have its own costs and protections, while using DailyPay means having less of your wages left to arrive later.
Compared with a conventional budgeting app, DailyPay’s main point is not simply categorizing spending; it combines a view of earned pay with a way to access it early. If you already have enough savings to handle timing bumps, leaving your wages on their usual schedule may be simpler. If the same shortfall returns every month, adjusting your budget, bill dates, or savings plan may be more durable than repeatedly moving pay forward.
Who Can Benefit?
Honestly, I think anyone who receives a regular paycheck could find value in this app. It’s especially useful for hourly workers or those with fluctuating incomes. Having the flexibility to access your money when you need it can relieve a lot of financial stress.
For employers, offering DailyPay can be a fantastic perk for employees. It can increase job satisfaction and reduce turnover, which is a win-win for everyone.
Before relying on it for a deadline, I’d check the amount shown for access and the transfer timing in the app, then make sure the destination account is the one you intend to use. If you are setting it up for a particular bill, allow enough time for the transfer route you choose and keep a backup plan for anything that cannot be late. These small checks matter more than a polished interface when a payment date is close.
My household verdict
Overall, DailyPay On-Demand Pay is more than just an app; it’s a financial tool that provides flexibility and peace of mind. Whether you’re dealing with an emergency expense or simply want to avoid the wait until payday, this app has got your back. If you’re curious, I’d say give it a try. You might just find it’s the financial lifeline you didn’t know you needed.
My recommendation comes with one boundary: use it for deliberate cash-flow management, not as a reason to spend more freely. For a household that can keep the account personal, agree how shared bills are handled, and plan around the smaller amount left for payday, the flexibility can be genuinely useful. If you need a shared account, guaranteed extra income, or a lasting fix for a budget that does not balance, I’d look elsewhere first.
Highlights
- Access earned wages instantly.
- Improves financial flexibility.
- User-friendly interface.
- Secure and reliable transactions.
- Supports multiple payment methods.
Limitations
- Fees may apply for transfers.
- Limited to participating employers.
- May encourage overspending.
- App requires frequent updates.
- Customer support response time varies.
Frequently Asked Questions
01What is DailyPay and how does it work?
DailyPay is a financial app that offers employees access to their earned wages before the traditional payday. By using DailyPay, workers can transfer a portion of their earned income to their bank account, providing financial flexibility and eliminating the need to wait for the next paycheck.
02Is DailyPay safe and secure to use?
Yes, DailyPay employs advanced security measures to protect users' personal and financial information. The app uses encryption and secure connections to ensure data privacy. Users can feel confident that their information is safeguarded against unauthorized access.
03Are there any fees associated with using DailyPay?
DailyPay charges a small fee for instant transfers, while next-day transfers may be offered for free with some employers. It's important for users to check with their employer and the app for specific fee structures, as they can vary based on the company and payment method selected.
04Which employers support DailyPay?
DailyPay partners with a range of employers across various industries. To find out if your employer is part of the network, you can check the app or ask your HR department. The growing list of participating companies ensures many employees can benefit from this service.
05How does using DailyPay affect my regular paycheck?
Using DailyPay does not change the total amount you are paid. It simply allows access to earned income before payday. The amount accessed via DailyPay is deducted from your upcoming paycheck, ensuring that you still receive the remaining balance on your scheduled payday.


